
September 2, 2026
𝗔𝗿𝗲 𝗖𝗩𝗖𝘀 𝗿𝗲𝘀𝗵𝗮𝗽𝗶𝗻𝗴 𝘁𝗵𝗲 𝘄𝗼𝗿𝗹𝗱 𝗼𝗳 𝘃𝗲𝗻𝘁𝘂𝗿𝗲 𝗶𝗻𝘃𝗲𝘀𝘁𝗺𝗲𝗻𝘁?
We previously discussed the role of corporate VCs (CVCs) in financing European deeptech (see post here https://lnkd.in/p/dA_4HuCw)
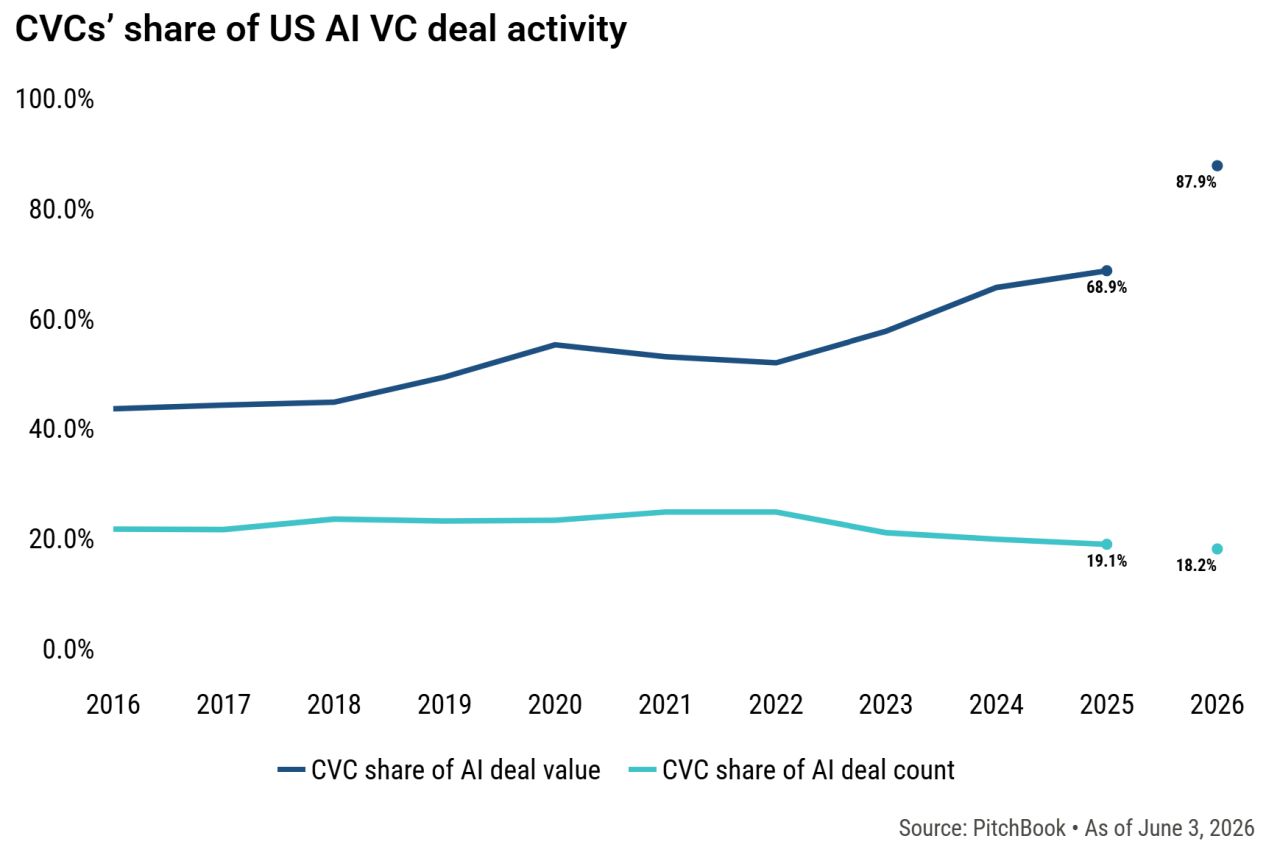
If anything, over the past year, 𝗰𝗼𝗿𝗽𝗼𝗿𝗮𝘁𝗲𝘀 𝗵𝗮𝘃𝗲 𝗯𝗲𝗰𝗼𝗺𝗲 𝗺𝗼𝗿𝗲 𝗶𝗻𝗴𝗿𝗮𝗶𝗻𝗲𝗱 𝗶𝗻 𝘁𝗵𝗲 𝘃𝗲𝗻𝘁𝘂𝗿𝗲 𝗺𝗮𝗿𝗸𝗲𝘁. This is of course partly due to the AI and defence supercycles (see chart below). But it is also the result of more corporates realising that they are slow on innovation and their innovation is often inherently expensive.
Corporates have also come to terms with the fact they are not necessarily the best investors, so it 𝗺𝗮𝗸𝗲𝘀 𝘀𝗲𝗻𝘀𝗲 𝘁𝗼 𝗮𝗹𝘀𝗼 𝗶𝗻𝘃𝗲𝘀𝘁 𝗶𝗻 𝗳𝘂𝗻𝗱𝘀 which provide expertise and clarity of purpose.
The reality is that 𝗰𝗼𝗿𝗽𝗼𝗿𝗮𝘁𝗲𝘀 𝗵𝗮𝘃𝗲 𝗽𝘂𝘁 𝗶𝗻𝗻𝗼𝘃𝗮𝘁𝗶𝗼𝗻 𝗼𝗻 𝘁𝗼𝗽 𝗼𝗳 𝘁𝗵𝗲𝗶𝗿 𝗮𝗴𝗲𝗻𝗱𝗮, and are now working on all facets of innovation: as LPs; as investors in external companies; as accelerators of their own innovation which may end in a separate entity (call it incubating, accelerating etc).
The reality is that 𝗰𝗼𝗿𝗽𝗼𝗿𝗮𝘁𝗲𝘀 𝗵𝗮𝘃𝗲 𝗽𝘂𝘁 𝗶𝗻𝗻𝗼𝘃𝗮𝘁𝗶𝗼𝗻 𝗼𝗻 𝘁𝗼𝗽 𝗼𝗳 𝘁𝗵𝗲𝗶𝗿 𝗮𝗴𝗲𝗻𝗱𝗮, and are now working on all facets of innovation: as LPs; as investors in external companies; as accelerators of their own innovation which may end in a separate entity (call it incubating, accelerating etc).
Among the 𝗿𝗲𝗰𝗲𝗻𝘁 𝗻𝗲𝘄𝘀:
➡️ Corporates as LPs:
▫️ European corporates have provided €3bn to the Scaleup Europe Fund (European Commission), a public/private partnership where public investment is “only” €1bn.
▫️BAE Systems and Airbus have been the cornerstone of new defence-related funds, namely Lakestar and Expeditions for BAES and E2D for Airbus.
➡️ Corporates as direct investors:
▫️ In AI, NVIDIA has been in a category of its own, has now become the world’s largest investor, and has made many investment in its own clients. But so have many of the cloud providers which have been investing in foundational AI model companies to sway their business (think of Microsoft/OpenAI, Amazon/Anthropic, etc).
➡️ Corporates as intrapreneurs
▫️ The highest profile example is probably Kirkland & Ellis, a large US law firm, which has set aside $500m to build its own AI platform.
▫️ We might also include the various financial institutions and PE funds which have made big bets on neoclouds, DC infrastructure in general, and various JVs to change vertical industries using AI (e.g. Bain Capital/Open AI’s DeployCo or Prometheus backed by J.P. Morgan and Goldman Sachs amongst others).
Global Corporate Venturing (#GCV), the leading corporate venturing event organiser and media authority, mused that from 3,000 today, CVCs might become 30,000 in 10 years’ time. Of course, a thought experiment, but also a clear indication of the direction of travel.
#CorporateVentureCapital #VentureCapital #AI #DefenceTech #Innovation
Sources :
>https://pitchbook.com/news/reports/q3-2026-fewer-deals-bigger-bets-how-corporate-capital-is-concentrating-us-ai-venture-activity
>https://globalventuring.com/corporate/overview/when-innovation-meets-capital-and-customers/
>https://globalventuring.com/corporate/overview/what-happens-when-we-go-from-3000-cvcs-to-30000/
Our Latest News

July 31, 2026
There are increasingly 𝘁𝘄𝗼 𝘀𝗲𝗽𝗮𝗿𝗮𝘁𝗲 𝗽𝗮𝗿𝗮𝗹𝗹𝗲𝗹 𝘂𝗻𝗶𝘃𝗲𝗿𝘀𝗲𝘀: 𝘁𝗵𝗲 𝗹𝗮𝗿𝗴𝗲𝗿 𝗶𝗻𝘃𝗲𝘀𝘁𝗼𝗿𝘀 – 𝗮𝗻𝗱 𝗼𝘁𝗵𝗲𝗿𝘀.
July 31, 2026
Accel’s new report on “Founder Factory 2026” makes interesting reading.

